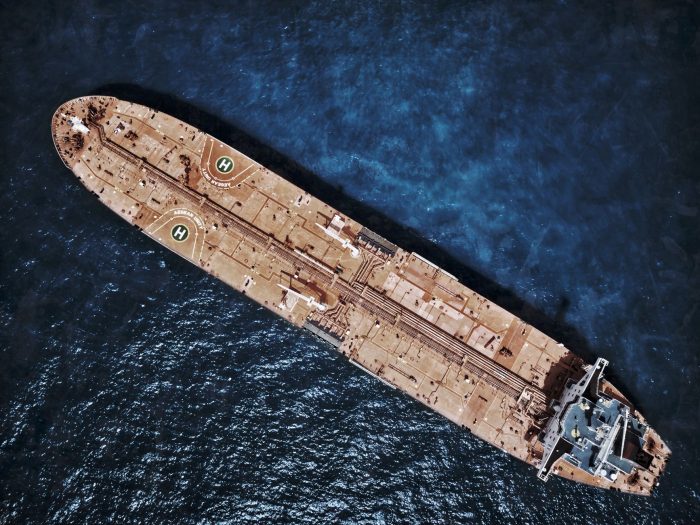
Oil prices jumped Monday as Iran renewed threats to tighten control over the Strait of Hormuz amid escalated US strikes, with Brent crude climbing toward $90 per barrel after a 20% rebound in July that reversed June declines. US commercial crude inventories stand at multi-decade lows following Strategic Petroleum Reserve draws, while OPEC+ continues incremental quota increases against a backdrop of partial regional output constraints.
The latest flare-up follows US airstrikes and Iranian abandonment of a prior interim agreement, with Tehran warning that future oil shipments may require approval. Flows through the strait, which handles about one-fifth of global oil trade, have operated at roughly two-thirds of pre-conflict levels according to officials, prompting rerouting by some vessels. Brent briefly topped $90 intraday before settling with gains, extending July’s recovery from earlier lows.
US crude stocks for the week ending July 10 totaled 409.7 million barrels commercially, down 1.7 million from the prior week and 6% below the five-year average, with the SPR at 316.5 million barrels, its lowest since April 1983. Combined inventories equate to about 42 days of supply at current refinery runs of 17.1 million b/d, versus a historical average near 65 days. Domestic production exceeds 13.5 million b/d, providing some offset.
OPEC+ core producers agreed in early July to add 188,000 barrels per day to August quotas, the latest monthly adjustment, even as Hormuz-related issues limit actual lifts for several members. EIA data show global supply dynamics shifting with inventory draws moderating after earlier conflict peaks. Major operators including Exxon Mobil and Chevron reported upstream resilience in Q1 filings despite timing effects from Middle East volumes.
Media narratives have stressed an imminent super-glut and sustained price pressure into 2026, yet July price action shows a 20% rebound driven by tangible supply risks rather than abstract oversupply forecasts. US inventories hit 42-year combined lows after SPR releases totaling 172 million barrels since February, countering surplus assumptions even as non-OPEC output remains elevated. Actual OPEC+ hikes remain partially unrealized due to on-ground disruptions, narrowing the projected surplus versus earlier IEA estimates of 4 million b/d.
SPR levels reached their lowest since April 1983 at 316.5 million barrels as of mid-July, with total US inventories reflecting aggressive draws amid the conflict that began in late February. US officials maintain the strait remains open for lawful shipping, with flows at two-thirds pre-conflict volumes despite Iranian claims on tanker incidents. Exxon Mobil’s Q1 disclosures highlighted $15.6 billion in cumulative structural cost savings since 2019, supporting distributions amid volume impacts. Golden Pass LNG Train 1 achieved initial production earlier in 2026, contributing to US export growth.








