The market seems to digesting a mix of positive and cautious signals. The gains in the S&P 500 and Nasdaq, largely driven by Nvidia’s strong performance, reflect ongoing optimism in the tech sector, while the Dow’s fluctuation suggests a more tempered sentiment overall. The significant drop in consumer confidence to its lowest level in over three years is concerning, as it may indicate growing worries about the economy and consumer spending, particularly with inflation still in focus.
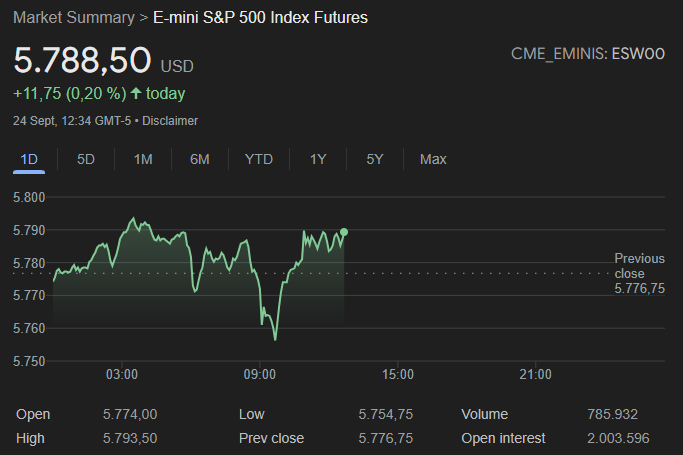
Chinese stimulus measures appear to have buoyed investor sentiment globally, as seen with the notable gains in Chinese stocks like Alibaba and JD.com, and this seems to be helping broader risk sentiment. Caterpillar’s rise also suggests some optimism about global infrastructure demand and potential economic recovery, particularly with China’s stimulus efforts.
The dollar’s weakness, driven by a rebound in the euro and expectations of further Fed easing, adds to the dovish outlook for U.S. monetary policy. Comments from Fed officials, including Atlanta Fed President Bostic and Fed Governor Michelle Bowman, have reinforced the view that inflation is cooling faster than expected, further supporting market bets for rate cuts.
With the PCE report coming later this week, investors will be closely watching for more clues on inflation trends and how the Fed might respond. The market’s current expectation of a 50 bps rate cut in November, with odds increasing slightly, reflects the uncertainty about how aggressively the Fed will move, especially with mixed economic signals like weaker consumer confidence and cooling inflation.
Overall, the market appears cautiously optimistic, with tech stocks leading the way, but economic uncertainty and Fed policy remain key factors influencing sentiment.
Enjoyed this article? Access highly trusted market research and educational content to expand towards advanced wealth creation with a membership.








