E-Mini S&P 500
Week’s Ahead with Review: E-mini S&P 500
The global IT outage disrupted the market to the downside in the overnight session, making it prudent to wait for a resolution of the issues, which led to a repair of the particular drop.
Every market story from The Private Banker, newest first.
The global IT outage disrupted the market to the downside in the overnight session, making it prudent to wait for a resolution of the issues, which led to a repair of the particular drop.
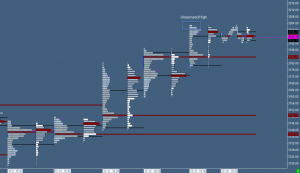
The prior session closed with a b-shaped profile structure, indicating a bullish session ahead.
Investors moving from high-growth tech stocks to sectors that benefit from lower interest rates.
Despite the strong one-time-framing behavior, the E-mini S&P 500 is showing signs of establishing a balanced approach.
Investors are anticipating US CPI and PPI data, as well as Fed Chair Jerome Powell’s testimony before Congress for insights on interest rates.
US Stock Performance: US stocks closed mostly higher with record closes for the S&P 500 and Nasdaq 100. The Dow, however, edged slightly lower.
S&P 500: Erased earlier gains, touched a fresh high of 5,500
US stock futures indicate a muted open on Wall Street as investors weigh a mix of economic data and remain cautious about the potential trajectory of technology stocks.
The consistent increase in durable goods orders, particularly in computers and transportation equipment, signals ongoing demand in key sectors.
Historic Balance Sheet Reduction: The Federal Reserve has been reducing its balance sheet at an unprecedented pace. Since
The market is trading slightly lower by about 0.2% as market participants seem to be adding to core long positions around the developing VWAP, targeting levels around 5540.
The call option volume for mega-cap growth and technology stocks has hit an all-time high. In recent weeks, the volume has more than doubled, highlighting an extraordinary level of bullish sentiment among investors.
The S&P 500 Technology Sector's price-to-sales (P/S) ratio has surged to an unprecedented ~10x, surpassing the previous 2021 record and even exceeding the levels seen during the peak of the Dot-Com bubble in 2000.
USD/JPY: Close to 160, hitting a fresh 34-year low.
The Congressional Budget Office (CBO) has revised its forecast for the US government's budget deficit for Fiscal Year 2024, increasing it from $1.5 trillion to $1.9 trillion, which equates to 6.7% of the Gross Domestic Product (GDP).
The financial landscape has undergone significant shifts, with short interest in major ETFs like the S&P 500 ($SPY) and Nasdaq 100 ($QQQ) dropping to unprecedented levels not seen in the past six years.
The recent pullback in the S&P 500 and Nasdaq 100, coupled with the performance of tech giants such as Nvidia, Microsoft, and Apple, reflects a classic scenario where market participants reassess their positions after a period of robust gains.
Equities: The S&P 500 and Nasdaq setting record highs, particularly with the surge in semiconductor stocks, suggests a strong bullish sentiment in the technology sector.
The European markets are currently in a holding pattern, awaiting further developments in UK inflation, the Bank of England's policy decisions, and political outcomes in France.
Retail Sales (May): Weaker than expected, indicating a slowdown in consumer spending.
Oil prices experienced modest gains on Tuesday, bolstered by geopolitical tensions in Europe and the Middle East, and mixed signals from Federal Reserve policymakers regarding future rate cuts.
WTI crude futures surged past $79 per barrel on Monday, marking the highest level in nearly three weeks.
The US Treasury projects net interest costs on the federal debt to reach an unprecedented $890 billion in 2024.
Goldman Sachs has revised its year-end target for the S&P 500 index to 5600, up from the previous target of 5200.