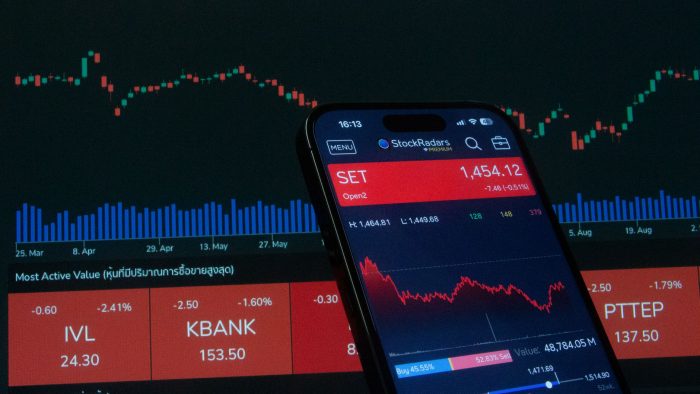
The December 2026 contract (ESZ26) was quoted at 7,860.75 in early U.S. hours, a gain of 34.50 points from the October 5 settlement of 7,826.25. The session range stood at 7,829.00 to 7,862.25, with volume near 149,000 contracts, about 36 percent of the 65-day average. On October 5 the contract settled 0.63 percent higher after trading between 7,760.25 and 7,847.50. The cash S&P 500 closed that session at 7,773.95, up 0.66 percent, while the Nasdaq Composite finished at a record 27,477.31, a 1.05 percent advance and its 23rd record close of 2026. The Dow Jones Industrial Average rose 0.18 percent to 51,273 and the Russell 2000 gained 0.50 percent to 2,847.
The Cboe Volatility Index closed October 5 at 15.52. Front-month VIX futures traded near 17.35 with the term structure in contango and skew elevated near 143. The 10-year Treasury yield stood near 5.27 percent to 5.32 percent on October 6, down from the prior close around 5.31–5.32 percent, while the 30-year yield had closed the previous session at 5.66 percent, its highest daily close in more than 24 years. West Texas Intermediate crude traded near 87–89 dollars a barrel after earlier declines linked to reserve releases.
September nonfarm payrolls rose 29,000, below the roughly 90,000 consensus, with the unemployment rate at 4.2 percent and average hourly earnings up 0.1 percent month-over-month and 3.0 percent year-over-year. August payrolls were revised lower. CME FedWatch probabilities for a 25-basis-point increase at the October 28 Federal Open Market Committee meeting fell to about 22 percent from roughly 64–70 percent before the report. The federal-funds target range remains 3.75–4.00 percent after the September hike. September ISM Services printed 54.9 versus 55.0 expected and 55.4 prior; the prices-paid component rose to 74.0 from 72.6. August core PCE inflation held near 3.0 percent year-over-year. Bottom-up estimates for third-quarter S&P 500 earnings growth stood between 24.1 percent and 29.5 percent year-over-year as of late September, the eighth consecutive quarter of double-digit growth, with technology a primary contributor. Technology accounted for about 40.3 percent of S&P 500 index weight as of the October 5 close. Nvidia rose 2.12 percent on October 5 to a record, lifting its market capitalization near 6 trillion dollars.
CFTC Commitments of Traders data for the week ended September 29 showed large speculators net short 142,499 E-mini S&P 500 contracts, a reduction of 9,271 from the prior week, while commercials were net long 35,281. Open interest stood at 1,895,922 contracts. On October 5, 311 S&P 500 constituents advanced and 189 declined.
Growth indicators remain positive on a year-over-year basis, with business surveys above 50 and prior-quarter GDP at 2.2 percent seasonally adjusted annual rate, yet monthly payroll momentum has decelerated. Inflation metrics stay above the Federal Reserve’s 2 percent target on a year-over-year basis even as shorter-term annualized core rates have moderated. Policy and liquidity conditions are restrictive relative to the post-2020 period, reflected in the recent rate increase and Treasury yields above 5 percent across much of the curve.
Consensus third-quarter earnings growth estimates rose rather than declined into reporting season, climbing roughly 1.4 percent on a bottom-up EPS basis from June 30 to September 30 and reaching as high as 29.5 percent year-over-year in some aggregates, even as September payrolls undershot forecasts by more than 60,000 and the three-month average gain slowed to about 51,000. The index advance on October 5 occurred alongside a 10-year yield still near 5.3 percent and a 30-year yield at a 24-year closing high, contrary to the pattern in which sustained yield increases above 5 percent have previously compressed equity multiples. Technology’s 40.3 percent index weight and Nvidia’s move toward a 6 trillion dollar capitalization accounted for a disproportionate share of the cash-index gain, while the equal-weighted cohort and several cyclical sectors lagged on a multi-week basis. Implied volatility remained near 15.5 despite the yield backup and the drop in October hike odds, leaving the volatility risk premium positive but compressed relative to periods of comparable rate volatility.
Large-speculator net shorts in E-mini S&P 500 futures increased in absolute terms earlier in September before the modest reduction reported for the week of September 29, leaving leveraged funds net short 372,489 contracts as of that date. The ISM Services prices-paid index at 74.0 marked one of the higher readings of 2026 even as the headline activity index held steady near 55. September average hourly earnings growth of 3.0 percent year-over-year was the slowest pace in the current expansion and below the 3.1 percent consensus. Open interest in the E-mini complex near 1.90 million contracts is below the mid-September peak above 2.4 million. Early October 6 volume in the December contract ran well below its recent average, consistent with a light data calendar ahead of the August trade balance and the New York Fed Survey of Consumer Expectations.








