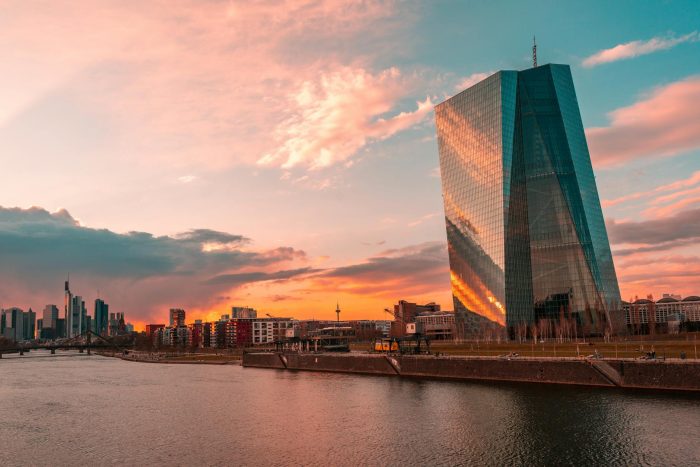
The anticipated rate cut by the European Central Bank (ECB) reflects the institution’s commitment to supporting economic growth amid subdued inflation and global uncertainties.
The widely anticipated 25 basis point rate cut on December 12, 2024, would bring the ECB deposit rate to 3.00%. This adjustment aligns with the ECB’s dual objectives of maintaining price stability and addressing the ongoing stagnation in economic growth.
With inflation decelerating to the ECB’s 2% target, the central bank has room to ease monetary policy without risking price instability.
Stagnant growth over the past 18 months and a cloudy medium-term outlook highlight the need for accommodative policies to stimulate the Eurozone economy.
Divergent views among ECB members underscore a cautious approach: Governors like Olli Rehn and Yannis Stournaras advocate for continued monetary easing, reflecting the urgency of addressing growth challenges. Robert Holzmann supports limited easing but warns against over-aggressive rate reductions, signaling potential friction in future policymaking.
Markets are pricing in at least four additional 25-basis-point cuts in 2025, potentially reducing the deposit rate to 2.00% by year-end. These expectations highlight the ECB’s likely sustained accommodative stance amid ongoing growth challenges.
Rising trade uncertainties and geopolitical risks could necessitate more aggressive easing, adding pressure on the euro and affecting the Eurozone’s external trade dynamics.
A weaker euro against the dollar could provide some competitiveness boost for exports but also raise import costs, complicating the inflation outlook.
Strategic Implications for Stakeholders
- Fixed Income Markets:
- Opportunities in Eurozone Bonds: Lower rates could support Eurozone government and corporate bonds, particularly those with longer durations, as yields adjust to the easing cycle.
- Search for Yield: Investors may seek higher-yielding alternatives outside the Eurozone, increasing capital flows into emerging markets and U.S. assets.
- Currency Markets:
- Weaker Euro Expectations: Continued rate cuts and global trade tensions may weaken the euro, providing opportunities for tactical short positions. Export-oriented Eurozone companies could benefit, but importers may face higher costs.
- Equity Market Impacts:
- Support for Growth Sectors: Lower rates may provide tailwinds for interest-rate-sensitive sectors like real estate, utilities, and consumer discretionary.
- Export Boost: Companies with significant exposure to global markets may gain competitiveness from a weaker euro, enhancing their revenue prospects.
- Corporate and Economic Strategies:
- Borrowing Costs: Lower rates will reduce financing costs, providing opportunities for Eurozone businesses to invest in expansion and innovation.
- Downside Risks: Persistent geopolitical tensions and trade uncertainties could undermine the effectiveness of monetary easing, requiring businesses to maintain flexibility and resilience in their strategies.
Monitoring Points
- December 12 ECB Meeting: Watch for policy guidance on the trajectory of future rate cuts and updated economic forecasts.
- Global Trade and Geopolitics: Developments in global trade relations and geopolitical risks will play a critical role in shaping the ECB’s policy path and market reactions.
- Eurozone Economic Data: Indicators like GDP growth, industrial output, and consumer sentiment will provide insights into the effectiveness of the ECB’s measures.
Enjoyed this article? Access highly trusted educational content and market research by investing in a membership.








