- The Dow Jones surged over 150 points, while the S&P 500 and Nasdaq rose by approximately 0.5%. Chinese stocks Alibaba and JD.com experienced gains of 2.6% and 2.3% respectively, following China’s announcement of a reduction in trading tax.
- 3M’s stocks recorded a notable increase of more than 6% after news broke that the company had tentatively agreed to a $5.5 billion settlement to resolve over 330,000 lawsuits related to defective earplugs.
- Tech stocks showed mixed performance: Meta and Alphabet gained 1% and 0.5% respectively, while Tesla fell 1% and Amazon saw a 0.5% decrease.
- The upcoming week is poised to be eventful in the United States, with investors closely tracking various economic releases, including the labor report, PCE price index, personal income and spending data, JOLTS job openings, ISM Manufacturing PMI, and the second estimate of Q2 GDP growth.
- The dollar index stabilized around 104, near its highest levels in nearly three months. This follows Federal Reserve Chair Jerome Powell’s speech at Jackson Hole, where he expressed readiness to raise rates further while maintaining a cautious approach.
- Powell acknowledged progress in easing price pressures and highlighted both the risks from the robust US economy and the commitment to bring inflation down to the 2% target level.
- The 10-year US Treasury note’s yield remained close to 4.25%, slightly below the recent 15-year high. Investors continue to assess the Fed’s monetary policy outlook and evaluate the impact of increased bond supply.
- Powell’s comments during the Jackson Hole Symposium indicated that borrowing costs are above the mainstream estimates of neutrality. Expectations of cautious policy transmission and potential rate hikes in the face of strong growth patterns persist.
- Risks to bond prices in the secondary market persist due to concerns over higher long-dated debt issuance from the Treasury in the coming month.
In the New York trading session, the E-mini S&P 500 experienced a rise of approximately 0.44%, accompanied by a slightly lower dollar and negative volatility, which could potentially offer support to the stock markets.
On the daily interval, the market appears to be moving towards the establishment of a balanced price range. This follows the market’s identification of possible core buying opportunities around the upper value extreme of the Year. As a result, investors are leaning on these particular extremes to explore potential rotational scenarios.
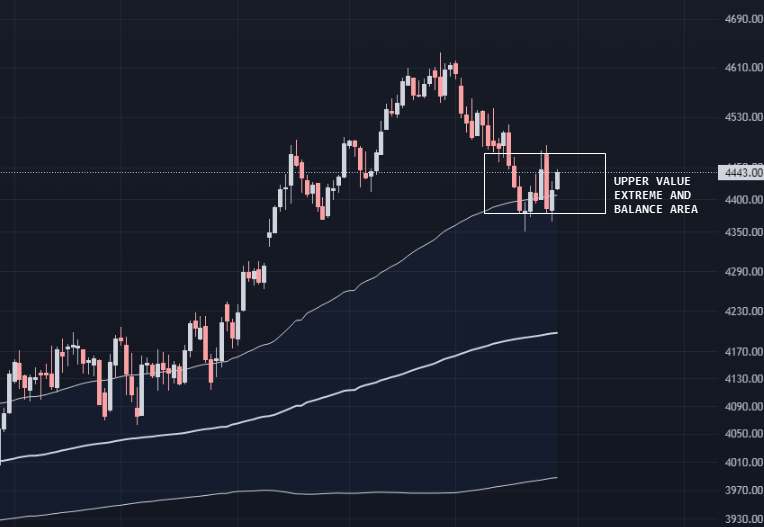
Analyzing the previous volume profile reveals a balanced structure, where the market’s auction shifted imbalanced above the price range of the previous day. This technical shift creates a bullish nuance in this session. However, absorption and potential long liquidations have emerged around the swing high, possibly leading to a later session pullback.
As of August 22, asset managers were observed building both new long and short positions. Conversely, the leveraged sector experienced long liquidations and the establishment of new short positions. This mixed behavior in the managed money sector may signal a degree of caution.
The current options landscape indicates a greater interest towards the put side of the market, particularly within the lower standard deviation area of the current price.
Enjoyed this article? Access exclusive market insight for advanced wealth creation with membership.








