The US stock market is displaying a mixed outlook before the New York trading opening, with the S&P 500 Futures up by 0.1%, Nasdaq down by 0.2%, and the Dow Jones up by 0.2%. Investors are eagerly waiting for the inflation report due on Wednesday to determine the path of prices and monetary policy.
PacWest’s rise by 34%, after cutting the quarterly dividend, has slightly calmed the mood of investors regarding the concerns of the banking sector. The earnings season is nearing its end, but companies such as Disney and PayPal are yet to report quarterly results this week.
On the daily interval of the E-mini S&P 500 Futures contract, Friday’s rise of about 1.8% from the lower extreme of the current balanced price range was initiated by the potential halt of interest rate hikes, which led to the dollar weakening to support equities and commodities.
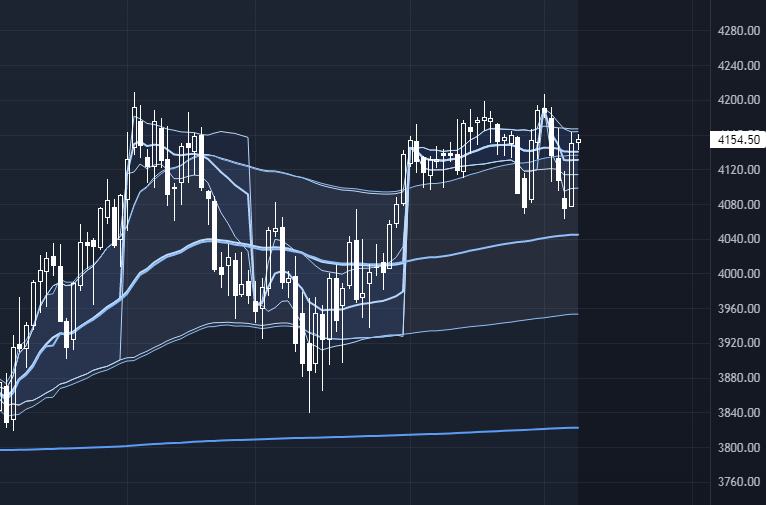
The market may target the upper extreme for possible absorption purposes, as the price swing between the particular extremes is getting wider. Internally calculated short-to-medium-term perspectives appear mixed, with a supportive stance towards a weakening dollar.
A more extended pause in the terminal rate hike path may potentially benefit the value of the dollar, which could create pressure on equities and commodities. However, investors currently seem to perceive such a pause as supportive for stocks.








