The yield on the T-Notes rose towards 3% as the rate is supported by the tighter monetary policy while the economy seems robust by the recent data releases despite the surging inflation and rising global interest rates. It seems that a 75bps rate hike is more favored than a 100bs rate hike, according to Fed Governor Waller and St Louis Fed Governor James Bullard. Investors may focus on the FOMC meeting on July 26th and 27th while more likely monitoring corporate earnings and housing market indicators to navigate through the market.
The T-Notes Futures fell by about 0.6% in this month of July, heading lower for several months and giving the market context a bearish bias for the lower periodicities. The daily is slightly below the EMA50 level which is quite rotational currently, therefore traders eventually lean on the extremes of the balanced price range to conclude rotational trades. The prior month closed with a buying tail via possible short covering behavior and may act as a supportive area in this month.
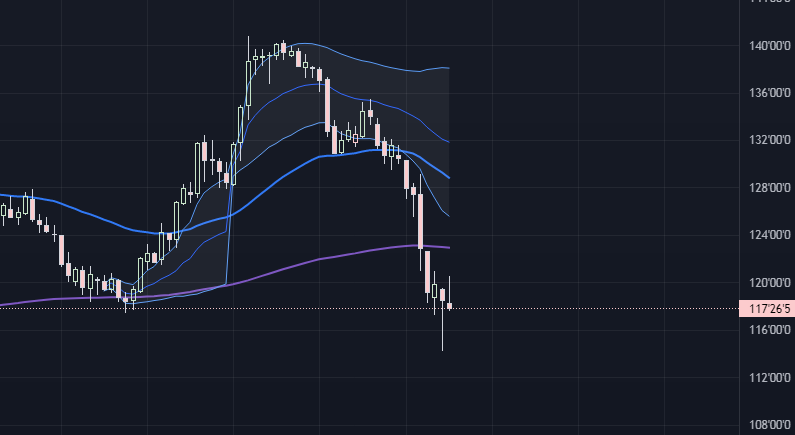
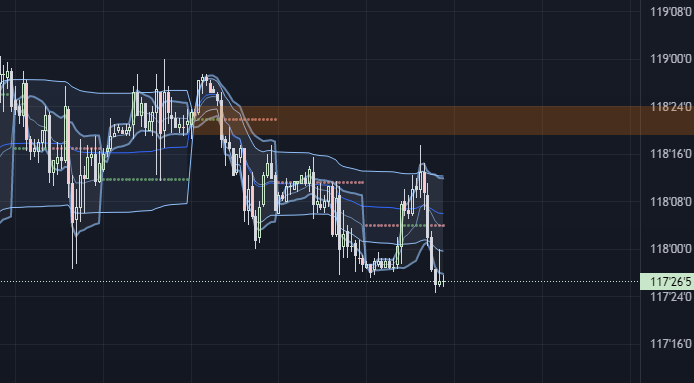
The short-term perspective found strong selling around the week’s upper value extreme in today’s trading session which led the market to fall towards the swing lows with current potential absorption via short covering and buying. The market may target the swing highs again as market participants might be adding shorts to core positions around the upper and prior VWAP close level as potential scenario.
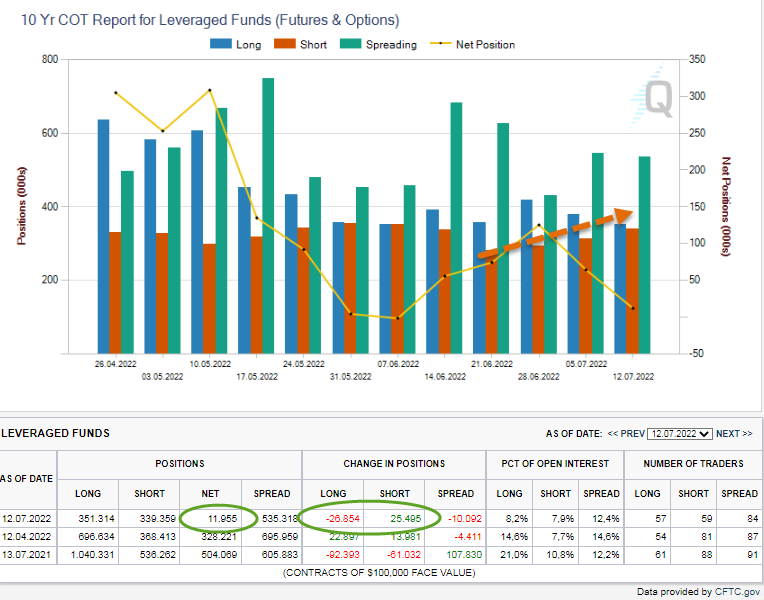
The Asset manager sector bought about 33.413 contracts of T-Note Futures as of July 12th data via new long positions and short covering with rising net long positions. Leveraged funds were net selling 52.349 contracts via long liquidations and new short positions – net hold short positions increased for the past several weeks in this particular sector, giving the market a mixed and balanced view from the professional’s data perspective.