Given the mixed dynamics in U.S. markets, our perspective highlights the importance of balancing risk exposure across equities, fixed income, and safe-haven assets as investors navigate evolving economic, geopolitical, and policy uncertainties.
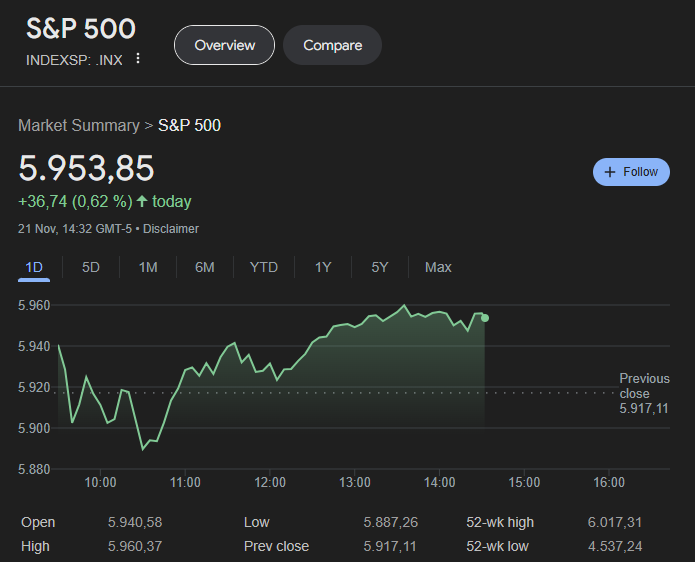
U.S. stocks extended gains on Thursday, with the S&P 500 and Nasdaq 100 rising nearly 0.5%, while the Dow surged 1.5%, reflecting sectoral rotation. Strong performances in industrials (Deere & Company +3.5%) and broader sectors offset declines in big tech.
Nvidia exceeded Q3 expectations but issued cautious revenue guidance, leading to a 1% drop. Meanwhile, Alphabet (-6%) and Amazon (-3%) dragged on indices, signaling that tech valuations remain sensitive to growth outlook adjustments and market expectations.
PDD Holdings’ 5% decline on revenue misses highlights continued pressure on Chinese-linked equities amid global demand concerns and geopolitical risks.
Mixed labor data suggests resilience in the U.S. economy. Initial unemployment claims fell to a seven-month low, reflecting continued labor demand, but rising outstanding claims indicate a potential slowdown in hiring momentum.
Comments from Fed governors presented a divided view on inflation and growth, leaving markets uncertain about the December rate decision. Odds of a 25bps rate cut have fallen significantly, from 83% last week to 56%, as persistent inflation and labor market strength bolster the hawkish argument within the Federal Open Market Committee (FOMC).
The dollar index remains close to two-year highs, reflecting reduced expectations for aggressive Fed rate cuts and safe-haven demand amid escalating geopolitical tensions. While the greenback gained against the Euro and Pound, it weakened against the yen, underscoring a nuanced currency market driven by varying risk perceptions.
Escalation in the Russia-Ukraine conflict, including Ukrainian strikes and renewed nuclear rhetoric from Moscow, is driving demand for Treasuries and gold as investors seek safety amid geopolitical uncertainties.
The yield on the 1-year U.S. Treasury note pulled back below 4.4%, reflecting heightened demand for safety alongside revised expectations for the Fed’s rate path. Resilient economic data and inflation concerns have tempered dovish bets, with Fed Funds futures signaling growing skepticism about a December cut.
Strategic Implications:
Equities:
- Sector Rotation Opportunities:
- Favor industrials and consumer-facing companies with strong earnings performance (e.g., Deere & Company) to capitalize on resilience in non-tech sectors.
- Exercise caution in big tech, where valuation sensitivity to growth expectations remains elevated. Selective exposure to high-quality, AI-driven growth names like Nvidia may still offer upside, but near-term volatility is likely.
- Earnings-Driven Focus:
- Monitor upcoming earnings reports to identify companies demonstrating pricing power and demand resilience, particularly in an environment where the Fed’s trajectory remains uncertain.
Fixed Income:
- Defensive Positioning:
- Maintain a short-to-medium duration focus as Treasury yields adjust to shifting Fed expectations. Increased safe-haven demand amid geopolitical risks supports selective exposure to Treasuries.
- Inflation-linked securities (TIPS) offer a hedge against lingering inflation risks, particularly as labor market strength continues to challenge dovish arguments.
Currency and Safe-Haven Assets:
- Hedging and Diversification:
- For portfolios with foreign exposure, consider currency hedges to mitigate risks from a stronger dollar, particularly for export-sensitive sectors and international investments.
- Increased exposure to safe-haven assets, such as gold and yen-denominated assets, can provide diversification amid heightened geopolitical uncertainty.
Monitoring Priorities:
Fed Communication and Economic Data:
- Pay close attention to upcoming Fed speeches and inflation data, as these will shape December rate expectations and broader market sentiment.
Geopolitical Risks:
- Escalation in the Russia-Ukraine conflict could exacerbate safe-haven flows, impacting currency, bond, and commodity markets.
Earnings Reports:
- Insights from key earnings reports will help gauge sector resilience and guide equity positioning in a bifurcated market.
Enjoyed this article? Expand your horizion with advanced and trusted educational content by investing in a membership to become part of our community.








