- S&P 500 and Nasdaq both see gains, while Dow Jones remains steady.
- Fed Chair Powell to speak at the Economic Club of New York, providing insights into monetary policy.
- Treasury yields remain at multi-year highs.
- Initial jobless claims below forecasts, continuing claims rise.
- Communication services sector leads in performance, followed by tech.
- Energy and real estate sectors lag behind.
- Tesla shares drop 6% following disappointing earnings report.
- Netflix surges over 14% after strong quarter for subscriber growth.
- Dollar index edges lower to 106.3.
- Powell expected to address interest rate path following strong US economic data.
- Fed Governor Waller adopts a “wait and see” approach.
- Surging Treasury yields and Middle East conflict add support.
- US 10-year Treasury yield hits new 16-year high at 4.98%.
- Initial jobless claims fall to 198 thousand, lowest since January.
- Recent economic data points to a robust US economy.
- Mixed comments from Fed officials, but commitment to maintaining restrictive borrowing costs to combat inflation remains.
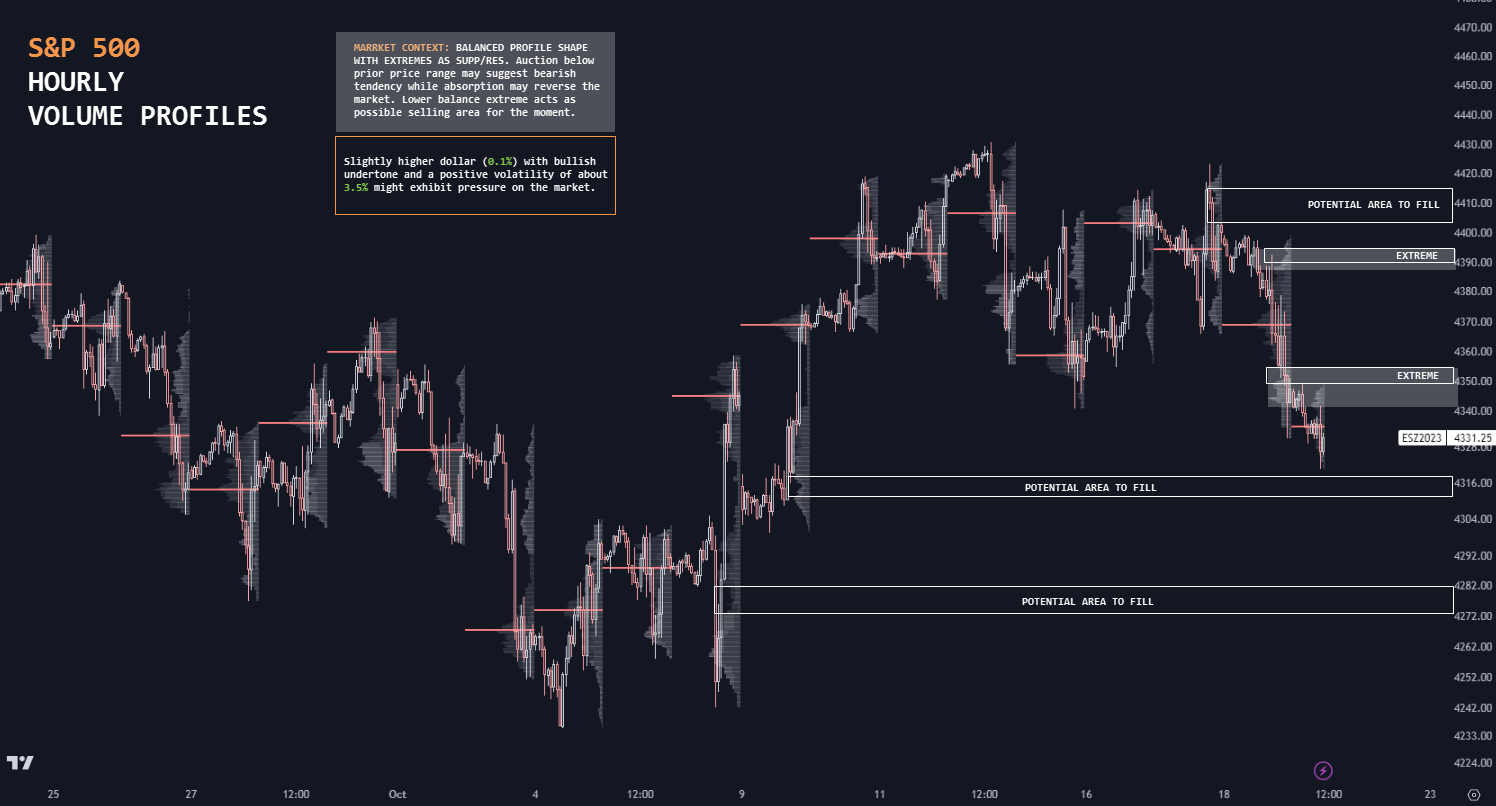
The E-mini S&P 500 is currently trading relatively unchanged. Initially, the market dropped towards the lows of the bracketing area on the daily interval to find absorption and short covering, allowing it to work its way back into the prior balanced price range. It appears to be targeting the upper extreme, while the lower extreme seems to be holding as resistance or a selling area of the prior balanced profile structure.
The lower dollar for the session, with a bullish undertone, might provide some support for the equities market. However, the presence of positive volatility at the moment could exert some pressure. This combination of factors may lead the market into a mixed and possibly balanced behavior, with traders attempting to discern rotational scenarios by focusing on the extremes.