- US stock futures edged higher on Wednesday, following a third consecutive day of gains in major averages during Tuesday’s session.
- Dow rose by 0.85%, S&P 500 rallied 1.45%, and Nasdaq Composite surged 1.74%, with technology, communication services, and consumer discretionary sectors leading the gains.
- Weaker-than-expected US consumer sentiment and labor data reinforced expectations of a potential pause in Federal Reserve interest rate hikes.
- The decline in Treasury yields, including the 10-year yield hitting a three-week low of 4.1%, boosted growth stocks.
- Upcoming releases of jobs report, PCE price index, and Q2 GDP figures will provide further insights into interest rate trends.
- Dollar index remained below 104 due to softer US economic data, aligning with bets that the Federal Reserve might halt rate hikes.
- JOLTS job openings declined, and consumer sentiment fell sharply in August due to concerns about the labor market, borrowing costs, and inflation.
- The market is waiting for the monthly jobs report, PCE price index, ISM Manufacturing PMI, and Q2 GDP figures for more clarity on interest rates.
- Federal Reserve Chair Jerome Powell’s Jackson Hole speech emphasized cautiousness in raising rates due to economic risks, while stating readiness if necessary.
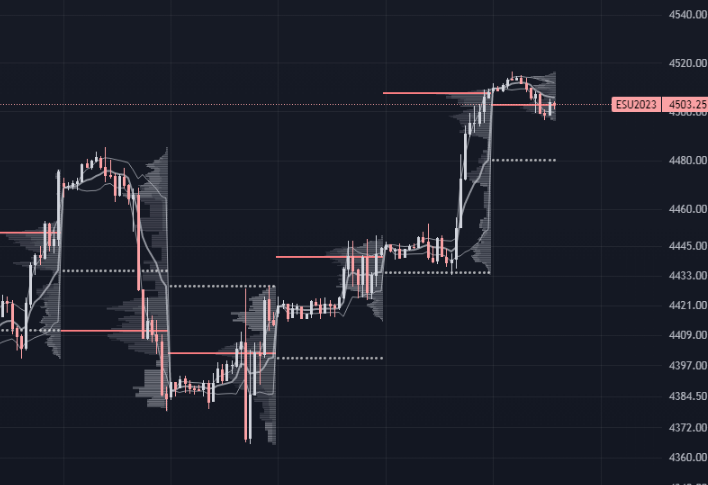
The E-mini S&P 500 has exhibited relatively little change in the overnight session following a notable surge in the previous session. This surge was triggered by the lower job openings data, which implies a potential slowdown in the labor market. This could have a dovish impact on monetary policy.
The minimal movement in the dollar might introduce a rotational bias to the market, while the elevated volatility could suggest a slightly bearish inclination towards a pullback to the prior VWAP close level. However, the increased volume observed around the highs and the Point of Control (POC) established in yesterday’s profile structure might indicate continued interest in higher prices.
The volatility landscape presents mixed signals, with the long-term perspective pointing towards a bullish market behavior and signs of mixed behavior emerging in this particular quarter and month. On the other hand, the short-term perspective leans more towards a bullish nuance, supported by negative volatility.








