All three major U.S indexes are up with about 0.6% in the European trading session. Investors are monitoring the energy crisis in Europe, with oil production cuts and liquidity preparations which might boost inflationary pressure.
Traders might be concerned about the aggressive stance towards monetary policy with potential further interest rate hikes.
The government yield is up by about 0.7% and the dollar rose 0.4% which eventually pressures the commodities sector as Gold is slightly up with 0.1%. The VIX, the volatility gauge for the S&P 500 index, pointing to a bearish behavior with minus 1.5%.
Upcoming are several speeches from Federal Reserve policymakers and new economic data such as today’s ISM Services figures which will give further guidance of the central bank’s path to hike.
Interesting enough to mention on the corporate site is that Volkswagen revealed its intention to list Porsche in an IPO and CVS Health announced that it would purchase Signify Health for about $8 billion.
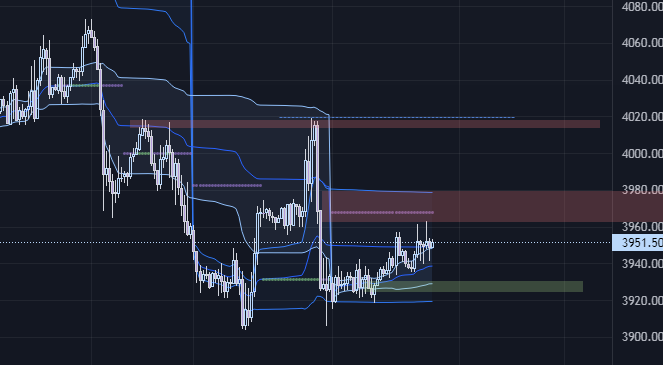
The daily interval of the CME:ES Futures contract found some buying around the Year’s lower value extreme which might lead to a bullish bias for the day.
However, the hourly interval shows some signs of bearish behavior such as swing failure and selling tails around the day’s highs while the New York trading session may be serving a buying flow in the opening hour.
The upper VWAP close level from Friday and the upper month’s value extreme could serve as resistance as lines in the sand upwards.
Swing highs from the prior week might be targeted for absorption purposes before it is hitting selling.