The U.S inflation rate surged to 9.1% vs 8.6% previously and higher than the forecast of 8.8%. Energy costs contributed the most to the rising prices with 41.6%. Food cost rose to 10.4%. Core inflation eased slightly to 5.9% vs 6% which excludes food and energy costs. The month to month data show an increase of about 1.3% vs. 1% and all sectors broadly seemingly increased with gasoline, shelter and food prices mostly.
The dollar index got boosted by the data and rose to about 0.4% with supportive buyers in combination with short covering around the lower week’s value extreme to the upper value extreme. The currency benefits from speculation of further aggressive rate hikes of about 75bps and monetary tightening as well as investors which look to hedge against rising inflation and recession risks. Additionally, the interest rate hike gap between the FED and the other nation’s central banks let the major currencies drop against the dollar.
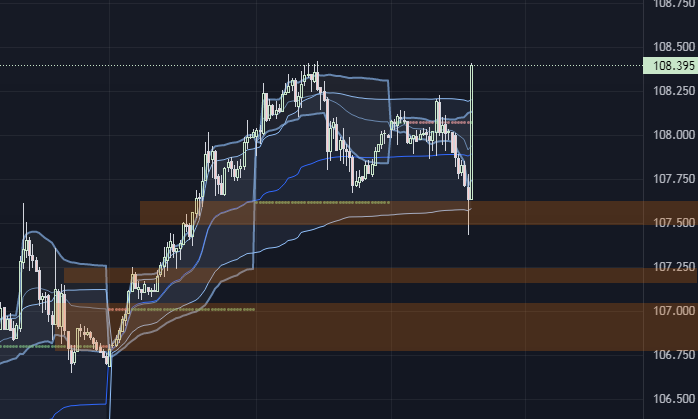
Resistance might emerge around the swing highs and the week’s upper DVAH level with potential long liquidations as the rising inflation should pressure the currency.