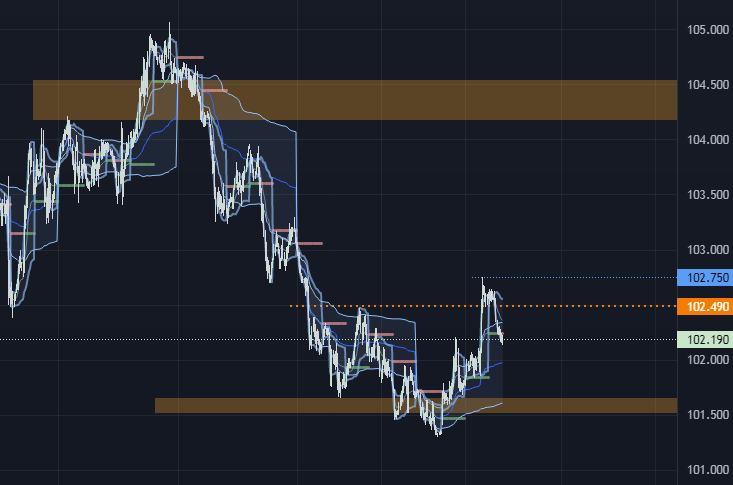
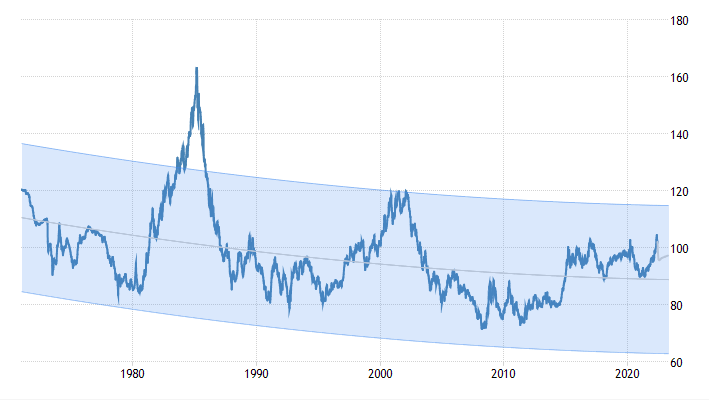
The dollar index (ICEUS:DX) fell about 1.1% in the month of May as the market found selling around the swing highs and bracket highs on the monthly periodicity. Rising government yields (10YR: 2.9%) supporting the greenback with potential further interest rate hikes and monetary tightening. Euro zone inflation gives clues about possible European hikes which may be able to pressure the dollar. Upcoming US nonfarm payrolls and inflation data for May eventually giving more clues about the U.S. economic health.
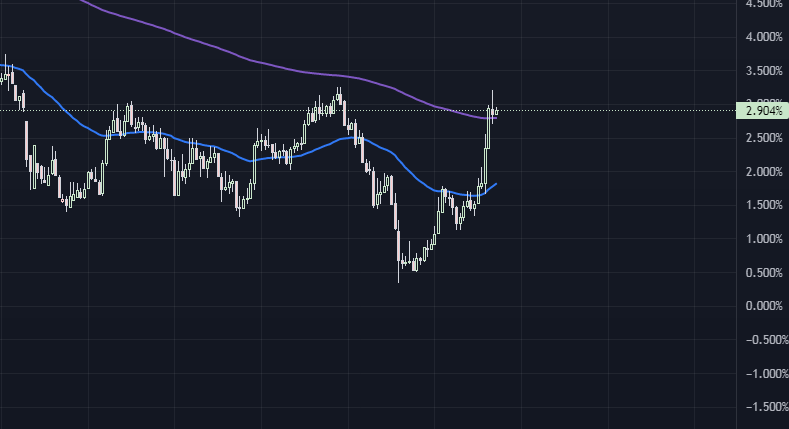
The 10 YR Government yield stands around 2.9% and closed the month slightly lower by testing the swing highs back from 2018 which may be able to retrace the rate. The current raising yield supports the dollar for the moment.
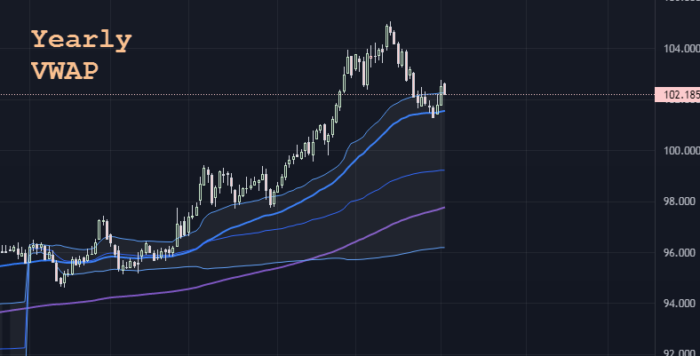
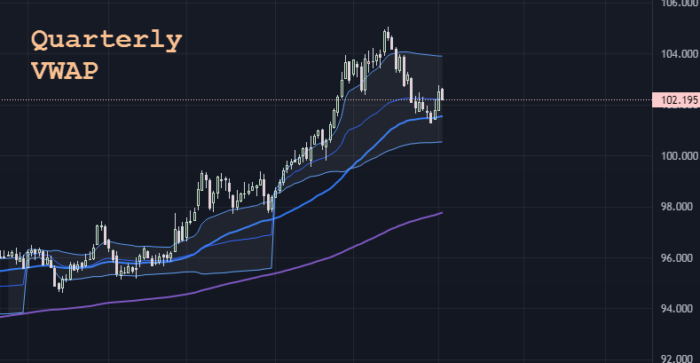
While the market closed with a swing failure on the monthly and forecasts pointing more likely to a bearish retracement, the dollar still have room to the upper macro standard deviation extreme. Looking at the Yearly VWAP we can observe supportive buyers off the upper value extreme which is confluent with the EMA50 on the daily bars chart. Moving forward to the Quarterly version we can observe trading in the middle of the Quarter’s value, giving signs of potential rotational behavior while the market closed below the monthly value close area.
The weekly format of the VWAP is imbalanced ot the upside as the market retraced around 0.4% in today’s European trading session. The market may find buyers around the current VWAP or DVAL to target the swing highs for absorption purposes. The day’s DVAH could serving as resistance with the upper VWAP close level in case of a surge.